From 6 April 2027, tax on rental income goes up by 4 points.
- Basic rate
- 20%24%
- Higher rate
- 40%44%
- Additional rate
- 45%49%
This particular Income Tax rise doesn't apply to limited companies. Whether moving your property into one pays off has to be worked out on your own numbers.
Run my numbers
A free 15-minute call. We'll ring you back within one working day.
Thank you. We'll call you back within one working day to book your call.
What's changing
| Rate | 2026/27 | From 6 Apr 2027 |
|---|---|---|
| Basic rate | 20% | 24% |
| Higher rate | 40% | 44% |
| Additional rate | 45% | 49% |
| Mortgage interest relief (Section 24) | 20% | 24% |
Mortgage interest relief is given at the property basic rate, so it rises with it. Last year's Budget had already set 22%, 42% and 47% for April 2027; the Budget on 28 October 2026 added another 2 points.
Own name or limited company?
In your own name
- Tax on rental profit
- 24% / 44% / 49% from 6 April 2027
- Mortgage interest
- Relief at the basic rate only, 24% from 2027 (Section 24)
- Budget change
- +4 points on today
Limited company
- Tax on company profit
- Corporation Tax 19% up to £50,000, 25% over £250,000, marginal relief in between. Not changed by this measure
- Mortgage interest
- Fully deductible as a cost
- Taking money out
- Withdrawing profit as dividends can mean a second layer of tax: 10.75% / 35.75% / 39.35% above the £500 allowance
Moving property into a company isn't free. It can trigger CGT and SDLT (companies normally pay the higher rates, including the 5 point surcharge), plus mortgage and legal costs. That's why it has to be worked out case by case.
Run my numbersHow it works
- 15 minutes
A quick call
Free, by phone or online. Tell us how many properties you have, your profit and your mortgage.
- Your numbers
We run the figures
Tax in your own name against tax in a company from 2027, including the cost of switching.
- Your call
You decide
You'll see which option pays. What you do next is entirely up to you.
If you stay with us: Self Assessment from £180 a year, SPV accounts from £500 a year, plus VAT, depending on scope.
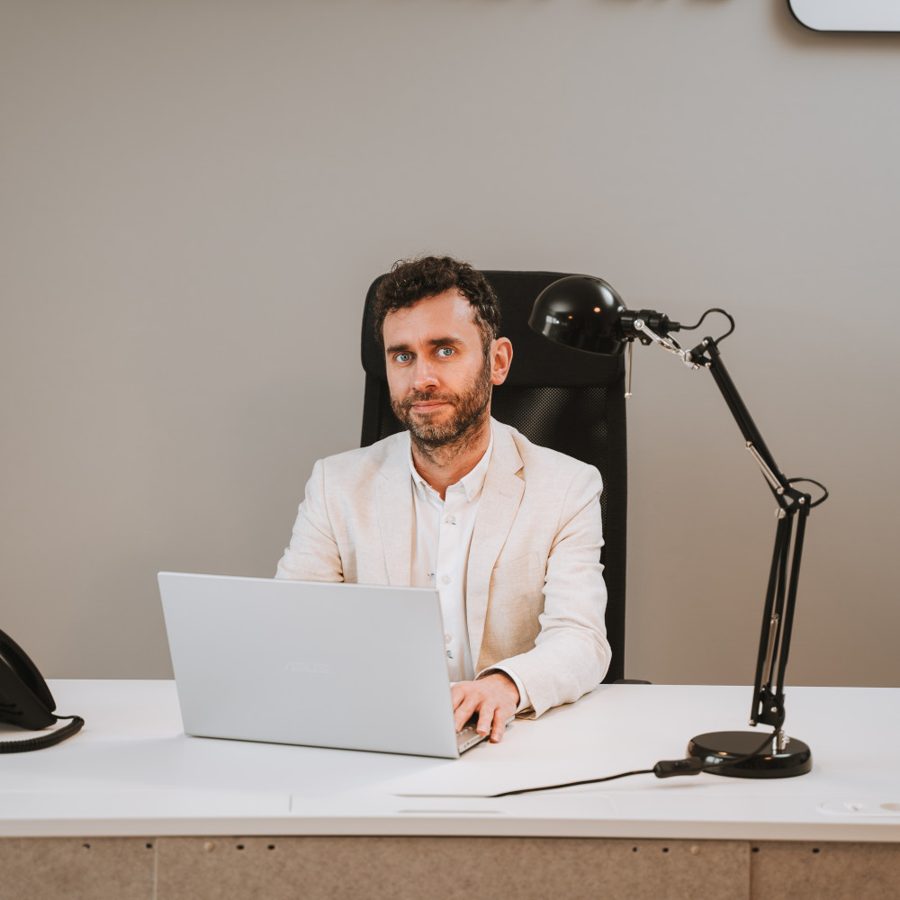
Monika and Marcin Udała
Accountants since 2010, a limited company since 2012. Based in Hyde, Greater Manchester, working with landlords right across the UK.
- Marcin Udała, ACMA (CIMA)Managing Director. Property tax.
- Monika Udała, ACCAChartered Certified Accountant. Company accounts and HMRC.
 We work in Xero
What clients say
5.0 on GoogleI found their services extremely helpful during revenue investigation with positive outcome. They immediately sorted any issues and problems.
We’ve been with Accountancy4You for over 12 years, and we couldn’t be happier. Their team is incredibly responsive, always ensuring our accounts are submitted on time.
They have been helping me navigate both personal and business tax matters with clarity and confidence for over 10 years now.
Know where you stand before April 2027.
Leave your number or give us a ring. 15 minutes, free and with no obligation.
0161 505 2712Mon to Thu 8am to 4pm, Fri 8am to 3:30pm
Run my numbers
A free 15-minute call. We'll ring you back within one working day.
Thank you. We'll call you back within one working day to book your call.
Applies to England, Wales and Northern Ireland. Scottish taxpayer status, rather than where the property is, decides whether Scottish rates apply; they aren't covered here. The Corporation Tax limits of £50,000 and £250,000 assume a full accounting year and are reduced for associated companies; the 19% rate requires eligibility for the small profits rate. Source: HMRC and HM Treasury, Budget 2026 (28 October 2026). The changes require the Finance Bill to be passed (Finance Bill 2026-27). General information, not tax advice.